All Categories
Featured
Key Advantages of Specialized Risk Policy Models
Finding Term Coverage for HIV-Positive Applicants

2026 Underwriting Changes to Impaired Life Coverage
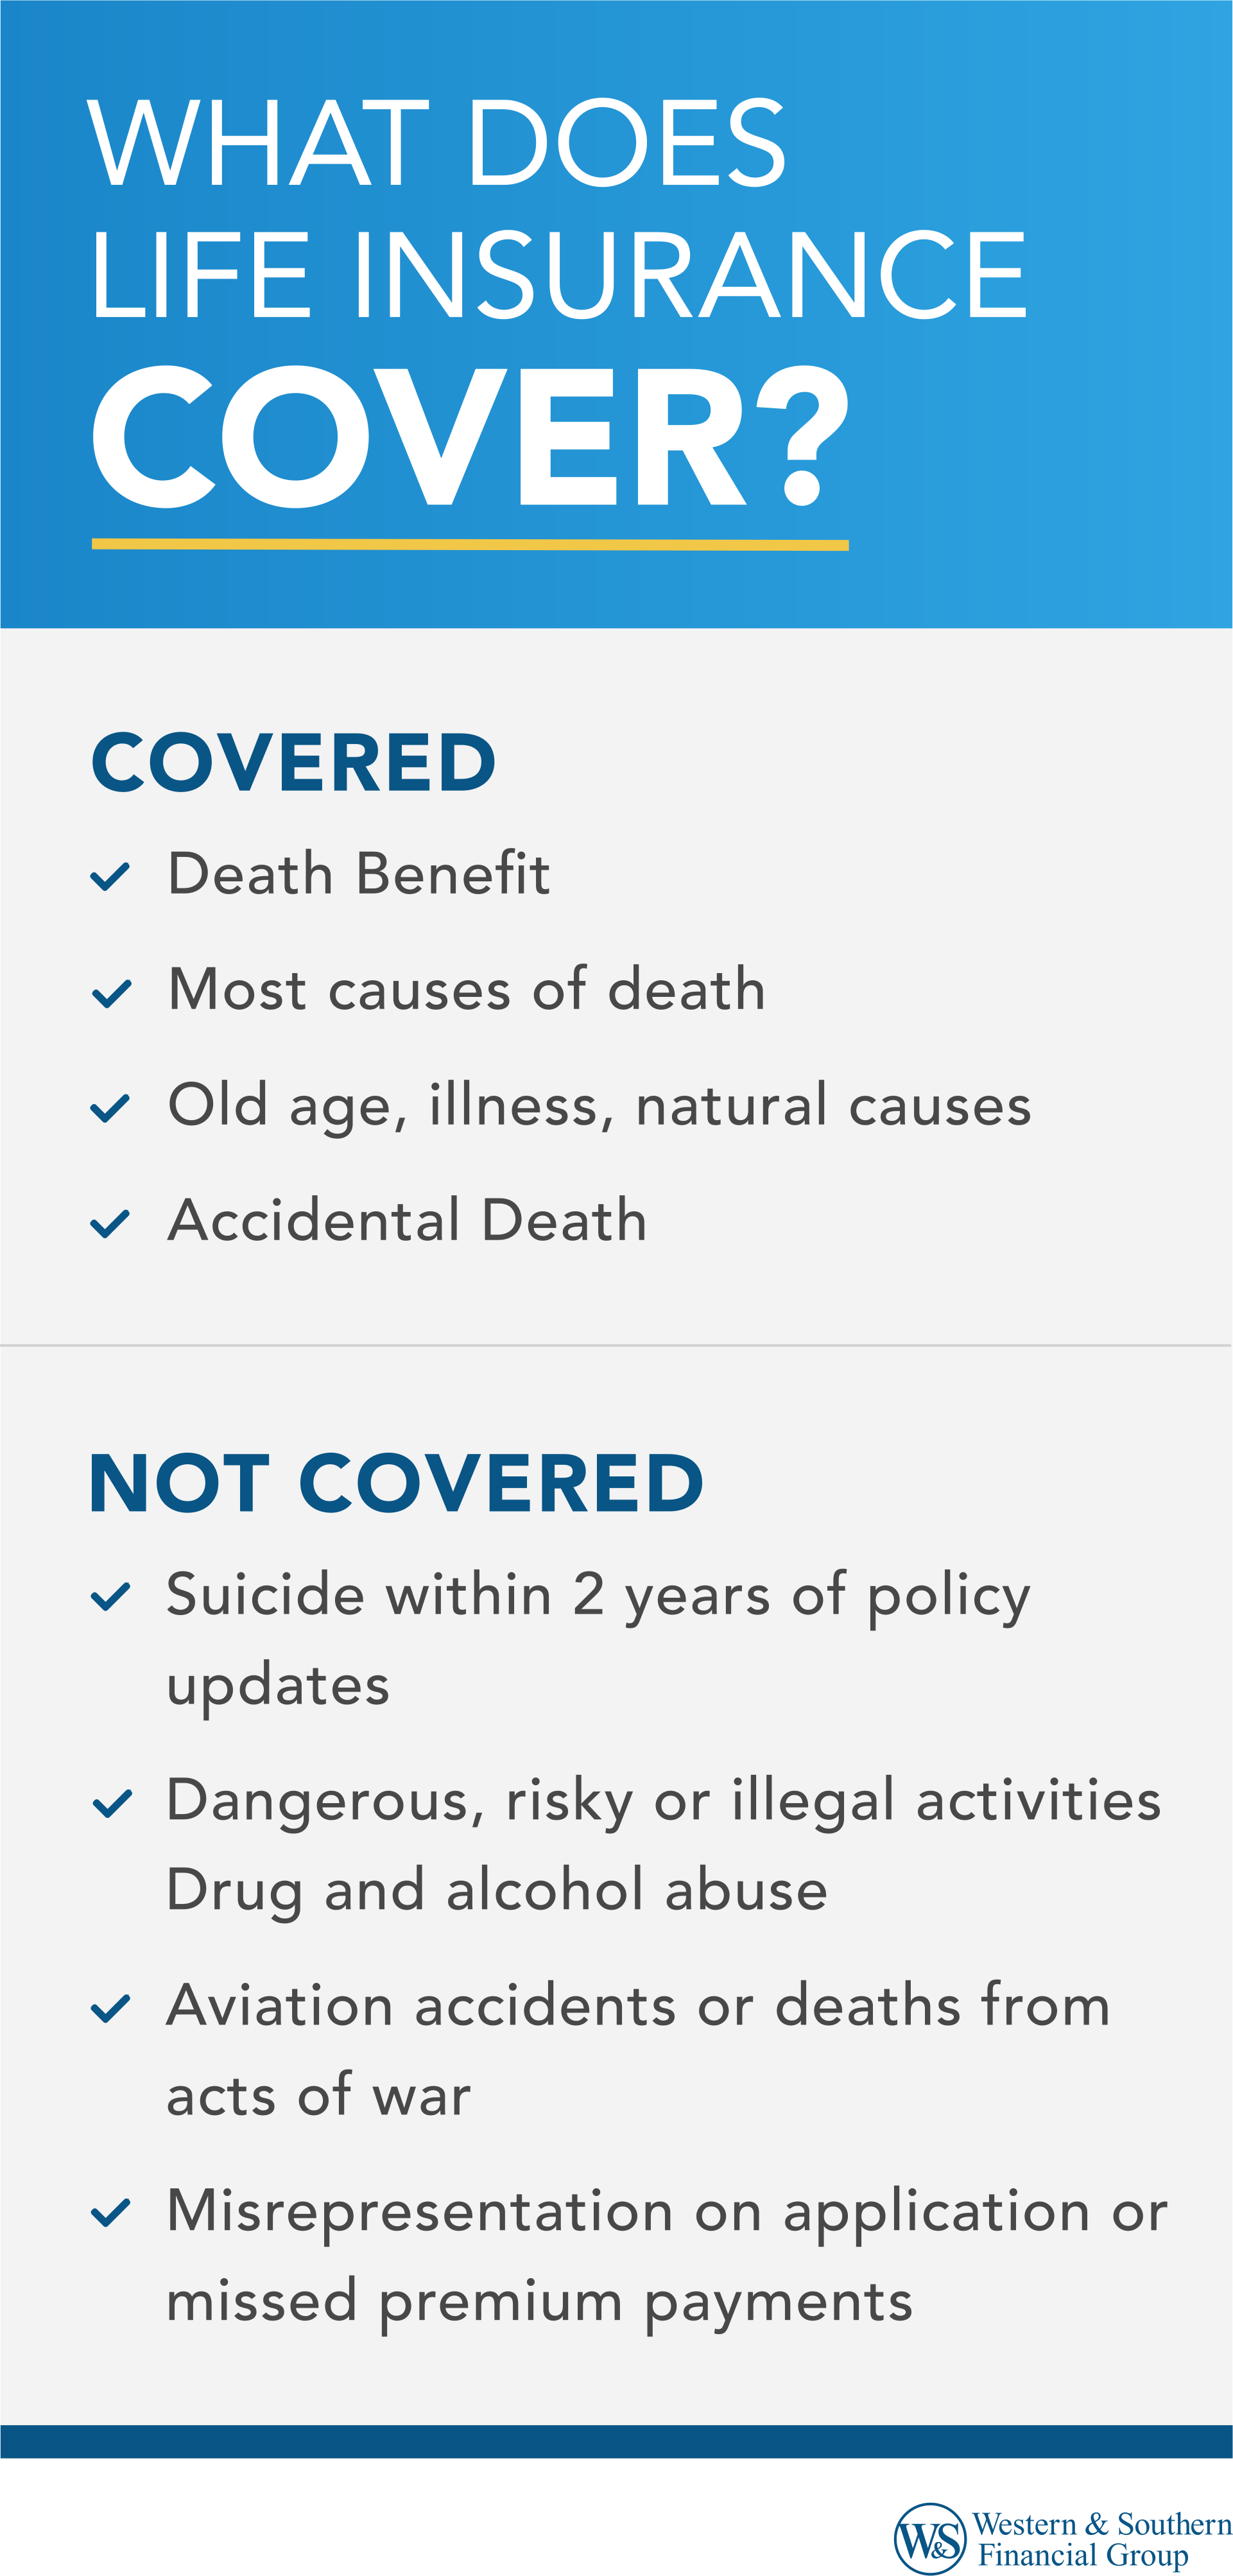
Injury insurance coverage may specifically cover HIV, but typically only for doctor and others at threat of getting the infection through their profession. Fully underwritten3 applications at Zurich for a person coping with HIV with an undetected viral load can apply for all cover types. Depending upon your health, we may provide some covers, subject to terms such as a higher premium, a shorter term policy, and/or exclusions. Insurers ask every consumer about their HIV status as part of the underwriting procedure for a life insurance policy. At Zurich we ask every consumer if they have actually ever had a favorable HIV test or are waiting for the outcomes of a test. There will be extra concerns asked if you divulge HIV positive status, which will have to do with when the diagnosis was, treatment, any problems or Help associated illness, and whether the HIV viral load is suppressed or undetected. If you inform us you're living with HIV and we have the ability to think about cover, we'll ask your dealing with physician for a report. The report ought to include as much as date blood test results, CD4 lymphocyte counts, viral load tests and details of your treatment strategy. If you don't have recent tests, we might ask you to get a blood test, either with a medical examiner of our option or through your treating medical professional. We'll ask about your height, weight, alcohol or leisure drug use, current and previous medical diagnoses and treatment, including mental health signs or medical diagnoses, history of sexually transferred infections. Those sorts of questions might appear intrusive, however we're just attempting to get the info we require to correctly examine any risks to your health, and these concerns are asked to all customers making an application for underwritten cover. If you are thinking about getting insurance and are concerned about any pre-existing conditions, it's smart to talk with a financial advisor before you use. They can describe your alternatives and support you through your application procedure. All insurance providers have different requirements. Not all insurance coverage business ask the same questions or need the exact same level of information. While we hope you select Zurich, we motivate you to get at least 3 quotes from different insurance companies to make certain you get the best cover at the best price for you. You could likewise ask your pals and associates who they have insurance coverage with and what their experience resembled. These policies frequently have' automated approval'however use just a certain level of cover. You should also inspect the policy's Product Disclosure Declaration(PDS)for a Pre-existing Exclusion Clause (PEC ). A PEC means you are not covered for any condition you had before getting insurance coverage. This might not be best for you. Life insurance coverage is a big financial investment, and it is worth paying an expert to get good suggestions. Access to life insurance coverage has improved in current years: lots of insurance providers acknowledge that lots of HIV-positive.
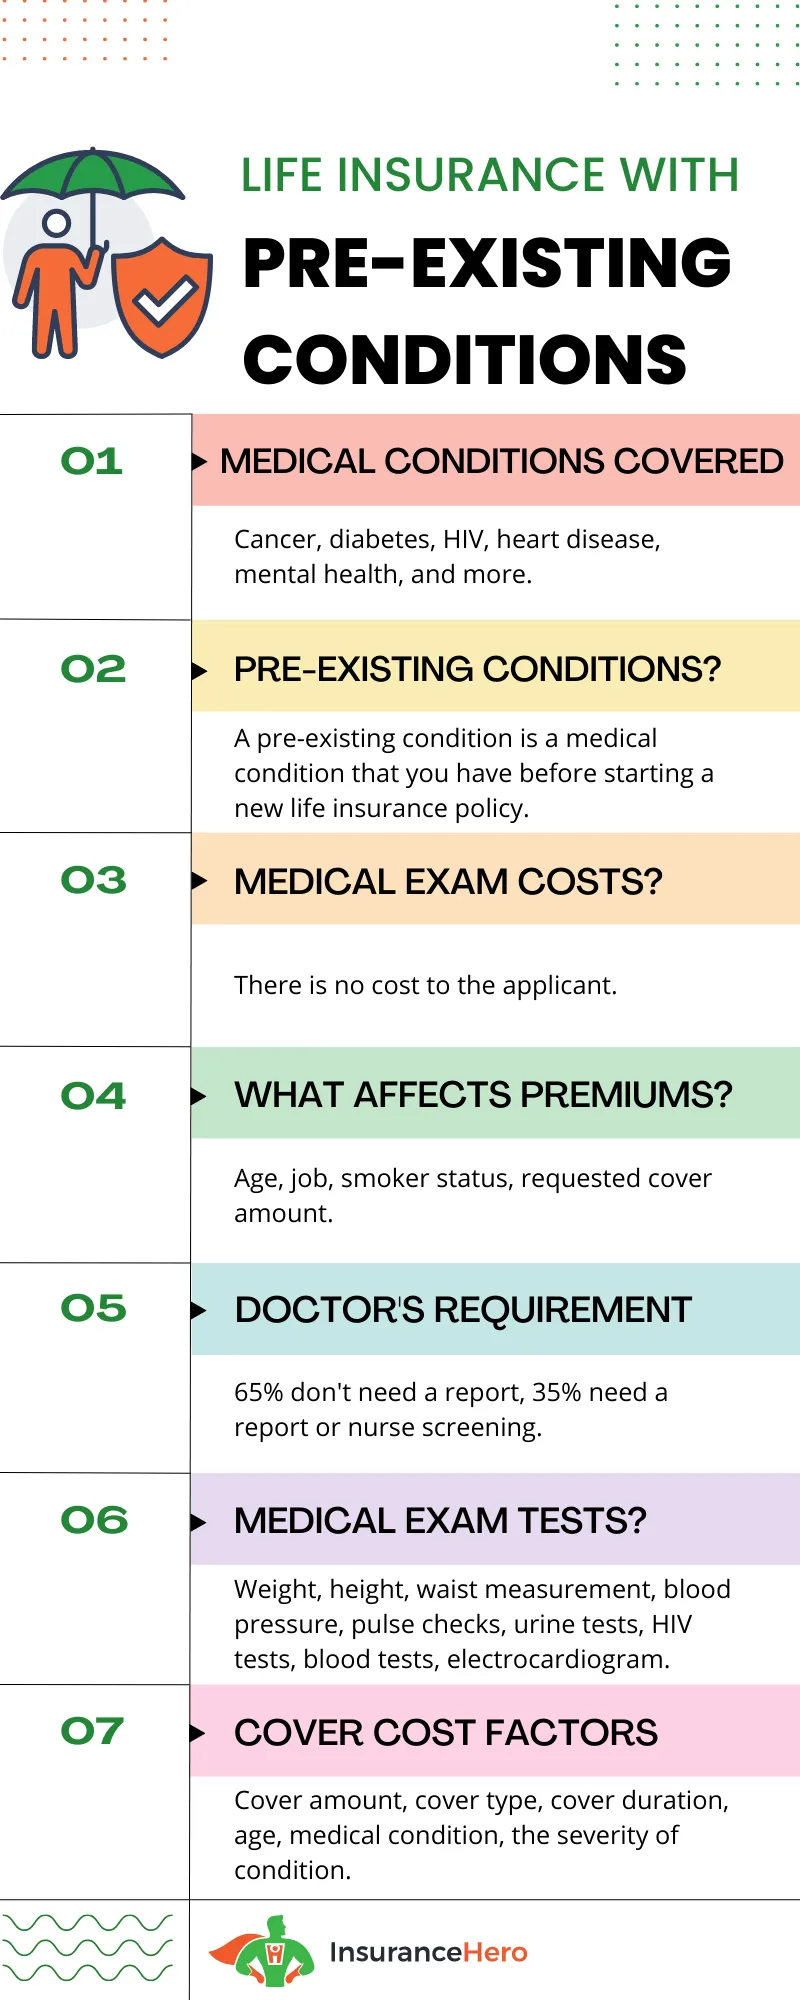
people have a near regular life span. When applying, you will be asked detailed concerns about your health. You will need to permit for the insurer to get more information from your physicians. This page reflects the personal financing market in the UK. Life insurance coverage (also
Group Critical Illness Insurancecalled'life assurance ','life defense','life cover'and 'death cover' )is typically created to pay out a cash amount to your enjoyed ones when you pass away. Not everybody needs life insurance, however if your liked ones depend on your earnings, if you have a home mortgage or if you have debts, you might wish to consider it. Insurance providers are increasingly identifying that people dealing with HIV are living to a typical life expectancy, however your viral load, CD4 and other pre-existing conditions may affect the life insurance coverage cover you can get, consisting of the premiums(regular monthly payments), length of policy and money sum paid. It's not a great idea to withhold details about your HIV status or to lie when getting insurance coverage. A series of organisations offer life insurance(including high street brokers, specialist brokers, life insurance coverage business, banks and building societies). Each insurance company has a procedure to evaluate whether you are eligible for life insurance with them; this process is called underwriting. Underwriting is utilized to evaluate the degree of danger (the probability that you might pass away at a younger age ). During the application process an insurance provider will ask you a great deal of individual concerns
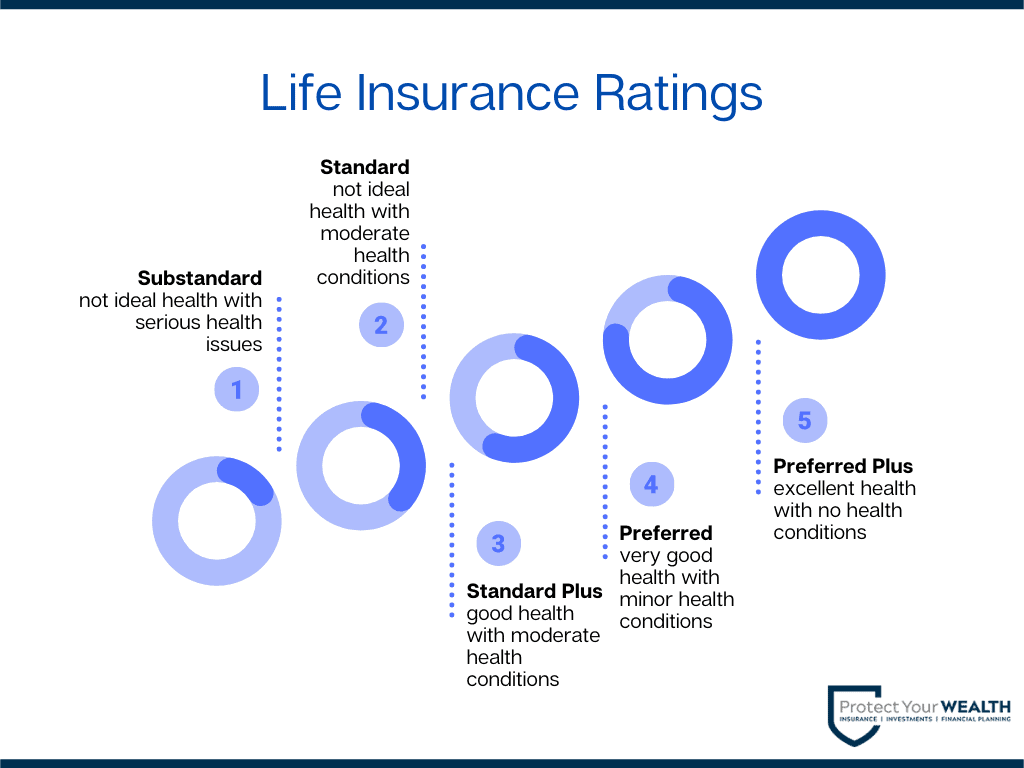
You may need to prepare yourself if you're not used to discussing your HIV status. You will likely be asked: When you were diagnosed What your CD4 count and viral load are What and how much medication you are taking What other health conditions you have If you have had any signs, now or in the past. Numerous insurance providers will ask if you have ever utilized drugs in your lifetime, while some will ask about drug use within the previous 5 or 10 years

Latest Posts

Why Custom Risk Underwriting Matters in 2026
Key Advantages of Specialized Risk Policy Models
Finding Term Coverage for HIV-Positive Applicants