All Categories
Featured
Key Advantages of Specialized Risk Policy Models
Finding Term Coverage for HIV-Positive Applicants


Why Custom Risk Underwriting Matters in 2026
Table of Contents
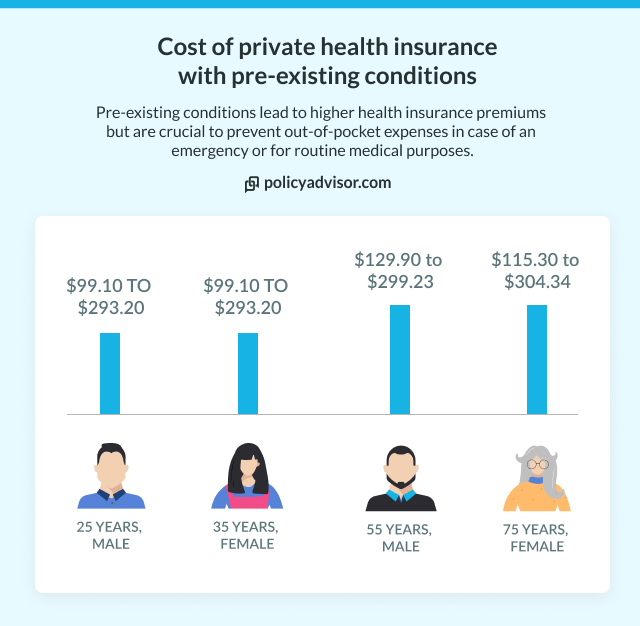
A pre-existing health condition doesn't suggest you can't receive a life insurance policy, however it simply impacts your available options and rates. Severe conditions such as cancer or a past heart attack may position you in a higher-risk category, a lot of individuals assume that they don't receive coverage.
You still have alternatives which's when impaired risk life insurance enters the image. It lets you get protection aligned to your threat aspect. Remember: You can get life insurance coverage with a medical condition. It's not constantly about the condition however what actually matters is the seriousness, date of medical diagnosis and how it's handled.
Whether you have medical or non-medical high-risk elements, you still likely have alternatives. The key is to match the policy alternatives to your objectives and present monetary or personal circumstances.
It is a hassle-free choice for those with critical health problems looking for guaranteed approval however at a greater premium and lower coverage amount.
Not all insurance providers might use comparable protection alternatives and ensured concern is not your only option. Different insurance providers may assess threat differently, so constantly compare quotes.
Timing matters, so wait if your condition is improving to qualify for better alternatives later. Even as an impaired-risk applicant, you might still be able to get coverage.
Here are some suggestions you might follow: Guarantee that your condition is well managed and you follow the treatment plan. Keep your medical records helpful to reveal stability in your health. Try giving up risky lifestyle practices like cigarette smoking or alcohol intake. Handle healthy way of life routines for weight management. Avoid using immediately after a condition is diagnosed.
Download and complete any appropriate surveys indicated based off the initial survey.
How to Secure Impaired Risk Insurance
Life insurance can be complicated, specifically when it comes to underwriting. This short article looks for to clarify life insurance underwriting by presenting clear, accurate information to assist you make notified choices.
Many companies now provide fast underwriting alternatives, which enable you to minimize the time necessary to get insured. This means you could get protection the fastest method without jeopardizing on thoroughness in its appraisal. Stay ahead of the industry with unique function stories on the leading companies, professional insights and the current news delivered straight to your inbox.
While it's real that health plays a large function in underwriting, insurers consider many aspects, consisting of age, lifestyle, and family medical history. Even if you have some health problems, you can still find competitive rates customized to your scenario. It's everything about discovering the right policy that matches your requirements and circumstances.
Medicare Chronic Condition ManagementEach policy type, the quantity of protection you want, and the examination will depend on it. For numerous policies, particularly those with lower coverage amounts, the procedure can be simple and does not need much time. Some even offer no-exam policies, which count on existing medical records and other information and make decisions based on that.
Insurers are eager to use cover to as lots of people as possible. To this end, they must guarantee that these premiums will be based on the level of the danger. Accurate assessment of one's threat will enable underwriters to offer a policy that protects one at a reasonable price.
Why Risk Underwriting Matters in 2026
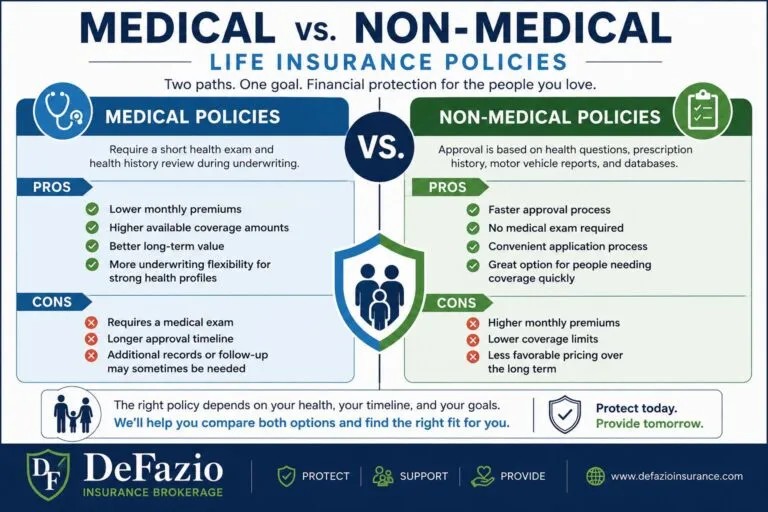
When you're taking a look at life insurance coverage alternatives, you'll likely desire the very best value for the finest cost. Medical underwriting is one aspect that may affect what you pay for your life insurance coverage premium. It involves your health and household case history and can increase or lower your payments. Let's have a look at how medical life insurance coverage underwriting can impact your policy.
Answers to concerns like, "Do you smoke?" or "What pre-existing conditions do you have?" when you're making an application for insurance may affect your premium. In the case of medical insurance, the healthier you are, the less you'll probably need to spend for your premium. Medical underwriting is a similar procedure for life insurance.
1 The insurance company takes an appearance at medical history, lifestyle practices, demographics, and other elements related to medical requirements. After an insurance company collects medical info, an insurance business will utilize analytical analysis to figure out the applicant's rate class and make a suggestion that best fits their situation.
Medical underwriting3 is simply one part of the entire life insurance underwriting process. Life insurance coverage business often also look at monetary status, such as income or personal bankruptcy history, throughout the life insurance coverage underwriting procedure. These factors assist an insurer offer the best rate based upon your distinct monetary circumstance.
Without verification that case history and other elements involving life insurance coverage do not pose a danger, a life insurance company might charge a greater premium to remain safeguarded. Depending upon how high of a threat an insurer determines a candidate to be, a premium might be lower or greater than average.
Medicare Chronic Condition ManagementProtecting Assets with Risk Coverage
In some cases, like when medical underwriting is not a requirement, life insurance underwriting might be finished in as little as 24 hours. The length of the medical underwriting process for life insurance coverage varies.

Latest Posts
Why Custom Risk Underwriting Matters in 2026
Key Advantages of Specialized Risk Policy Models
Finding Term Coverage for HIV-Positive Applicants