All Categories
Featured

Coverage for HIV Positive Applicants
Table of Contents
Life insurance can offer important monetary security for enjoyed ones, but those with preexisting conditions often have a harder time getting a life insurance coverage policy. Still, numerous medical conditions, consisting of diabetes, do not immediately disqualify a person for insurance protection. Most of the times, individuals with diabetes can still get life insurance; they might need to pay more than a person without a pre-existing condition.
In this article, we'll assist explain: Insurance coverage suppliers base premiums on the applicant's anticipated durability. Preexisting medical conditions can reduce life span, which is why life insurance for some diabetics tends to be costlier than it is for people without any pre-existing conditions. Even when blood sugar is well controlled, the disease can potentially cause issues, so it is a threat factor.
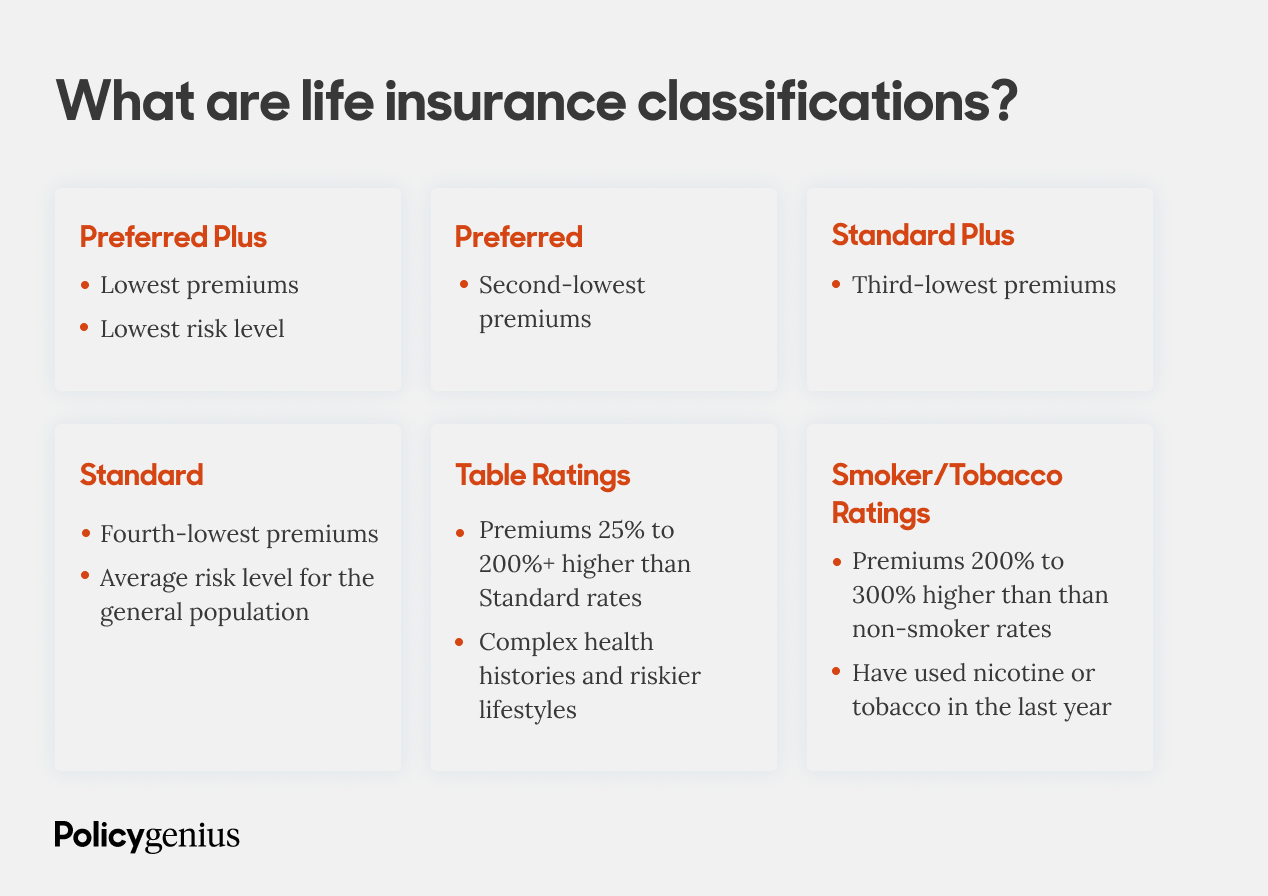
These include, but aren't restricted to: ObesityHeart diseaseHigh blood pressure (high blood pressure)HypertensionStrokeIssues with eyes, teeth, and other organsKidney illness or failureNeuropathyLimb amputationHowever, not all diabetics are the same. Life insurance companies rate applicant risk based upon a number of elements, including case history, household medical history, existing health, age, and way of life (such as tobacco use).
Applicants with well-managed diabetes and no issues might certify for more beneficial policy terms. The life insurance business will generally have you complete a medical underwriting procedure to determine your danger to guarantee. This can include a questionnaire that asks about your diabetes, in addition to the standard medical questions on the life insurance coverage application.
Dual-Eligible Medicare Medi-CalInsulin therapy, which is typically needed for Type 1 diabetes and often for Type 2 diabetes, might affect life insurance premiums. The insurer might likewise need medical records to confirm your health history. In addition, you will frequently need to complete a physical test (especially if you're looking for a high protection amount), and the life insurance coverage business might also need a microalbumin test, which can help find early signs of kidney damage.
Life Insurance Planning for Disabled US Trusts
full underwriting policies" below.) As part of the underwriting process, the life insurance coverage business will also inquire about the type of diabetes you have: Type 1 Diabetes, Type 2 Diabetes, or Gestational Diabetes. People with each form of diabetes can still get life insurance coverage, however depending on the base diagnosis, the application process may be more troublesome, and the coverage offerings more limited.
When it happens later on in life, that indicates it has affected your body and health for a much shorter length of time. However, Type 1 diabetes is typically detected in children or teens, making it a greater risk, and because of that, it is typically related to greater premiums. Type 2 diabetes is often diagnosed at a later age than Type 1, so it has less time to impact the body.
If that holds true, and you have actually learned how to keep it under control with diet and workout, you will likely get approved for the most affordable rates (in relation to others with diabetes). Even with Type 2 diabetes, individuals with diabetes-related problems and those who are insulin-dependent will find their life insurance choices more minimal and their premium expenses higher due to higher risk.

In a lot of circumstances, gestational diabetes goes away after delivering, however not always. In any case, pregnant women with gestational diabetes might wish to wait a number of months after delivering before using for life insurance. Presuming the diabetes goes away, it will then be much easier and cheaper to get a life insurance policy.
Lots of term policies can transform to permanent life insurance before the term ends without needing additional medical underwriting. If offered, conversion can be a choice to consider for individuals who purchased a term life insurance policy before they were detected with diabetes and want to extend their coverage.
Ways Cancer Survivors Can Obtain Life Coverage
2,3 It might be best to acquire as much life insurance as you'll need (and can afford) as quickly as possible, instead of wait to include more in the future. This is since life insurance coverage ends up being more pricey the older you get, and an underlying condition like diabetes will typically raise the cost even more.

Latest Posts
Evaluating Current Risk Assessments for Chronic Conditions

Finding Stability Through Life Insurance For Substance
Coverage for HIV Positive Applicants