All Categories
Featured


Protection for HIV Status Applicants
Table of Contents
With these policies, you may still need to complete a diabetes-related questionnaire and grant approval for the life insurance business to request your health records. The premiums are higher, however they might allow you to get protection you would not have the ability to certify for with a medical examination.
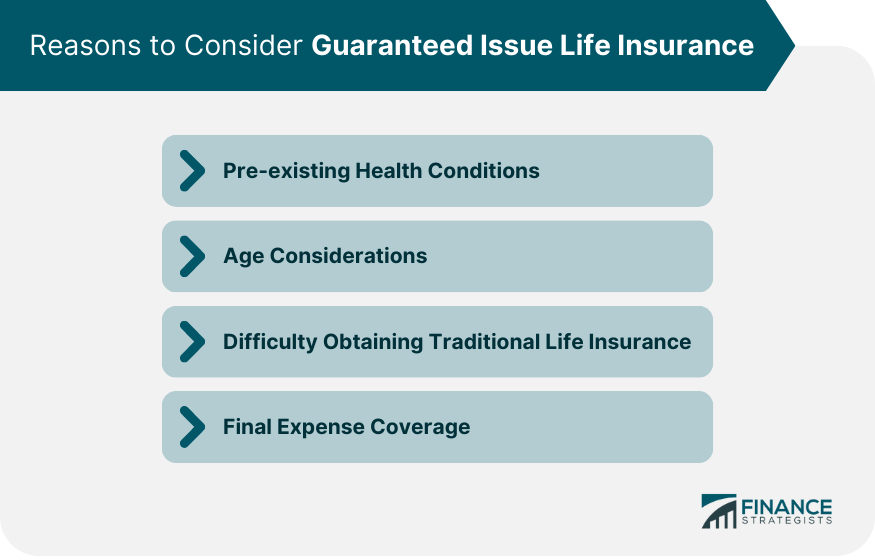
There is a possibility you may not be thought about for protection, even with a no-medical-exam insurance policy, due to your diabetes. In this case, a guaranteed-issue "final expense" policy may still be a choice, although a lot of the top life insurance companies don't offer them. Surefire concern life insurance is readily available without medical exams or health questions, making it accessible for individuals with severe health conditions.
These insurance coverage may only enable a maximum survivor benefit of $25,000 or less, and they frequently have a waiting period that can be as long as two to three years. That implies if you were to die before the waiting duration was up, your beneficiaries would not receive the full death benefit.
Modern Specialized Insurance Protection Strategies
Discovering the very best life insurance coverage for diabetics typically includes comparing policy features and seeking personalized suggestions to make sure the policy fulfills individual needs at an appropriate cost. Likewise, know that while getting life insurance coverage as a diabetic may need extra actions, there are options offered that may assist you get protection.
This will likely be your most affordable option, although you might just receive a restricted coverage amount. If you are buying individually, Guardian can put you in touch with a monetary advisor who can help you. Ensure to speak frankly with your representative and let them understand about your diabetes so that they can promote on your behalf.
Expand all Diabetes is thought about a pre-existing condition by insurance providers, which can affect eligibility and rates. Nevertheless, diabetics can and do obtain life insurance policies every day. Importantly, the kind of life insurance protection and the expense will depend, in part, on the kind of diabetes you have and whether you are keeping a healthy way of life that assists you handle your blood sugar level levels and symptoms.
Diabetes will impact the policy rates, however not always by the very same quantity. Type 2 diabetes is usually considered less of a threat than Type 1 diabetes, specifically if you are detected at an older age and can manage it with diet plan and workout. The finest answer is to talk with an insurance expert about your specific circumstance.
Medicare Savings Program Check
High Risk Travel Health Insurance for Impaired Patients
All insurance coverage needs are various. Diabetic life insurance premiums may be higher, but some elements can reduce the cost effect, such as the length of time the person has had diabetes, how well-controlled it is, and any medical test outcomes. In any case, a term policy will give diabetics more inexpensive life insurance security with a bigger survivor benefit compared to an irreversible policy, such as whole life insurance.
Life insurance coverage applications ask concerns about your health, and the procedure normally needs you to offer the insurer approval to access any health records required to confirm your info. In addition, you will normally require to have a medical examination as part of the underwriting procedure. They will try to find particular markers in your blood work and other tests that indicate an underlying medical condition whether you understand that condition or not.
Individuals and households can buy medical insurance through a Medical insurance Market (Marketplace) readily available in every state. Starting in 2014, all new health insurance coverage plans, whether sold inside or outside the Marketplace, can not reject protection, charge more, or refuse to cover treatments since you or someone in your household has diabetes.
A Health Insurance Coverage Marketplace is a method for individuals, families, and small organizations to shop forand comparevarious personal medical insurance choices all in one location. Plans used in the Market should meet certain requirements for advantages, consumer securities, and expense to the customer. Market strategies are separated into four different categories: Bronze, Silver, Gold, and Platinum.
In general, moving from Bronze to Platinum, expense costs get lower while premiums tend to get higher. Typically, anyone who purchases health insurance by themselves can buy it through a Marketplace. Only those who satisfy particular earnings requirementsand who do not qualify for budget-friendly job-based health coverage or certain other types of coverageare able to get monetary assistance paying for a plan acquired in the Marketplace.

Latest Posts
Evaluating Current Risk Assessments for Chronic Conditions

Finding Stability Through Life Insurance For Substance
Coverage for HIV Positive Applicants