All Categories
Featured
Key Advantages of Specialized Risk Policy Models
Finding Term Coverage for HIV-Positive Applicants

Specialized Coverage for Post-Treatment Cancer Survivors
Table of Contents
Understanding how carrier financial strength and underwriting appetite connect to each other is also important context our resource on what an insurance provider's AM Finest rating suggests covers the monetary strength measurement, and our resource on how do insurance brokers get paid covers why independent broker access to several providers consistently produces much better results after a decrease than using to a single carrier based upon name acknowledgment.
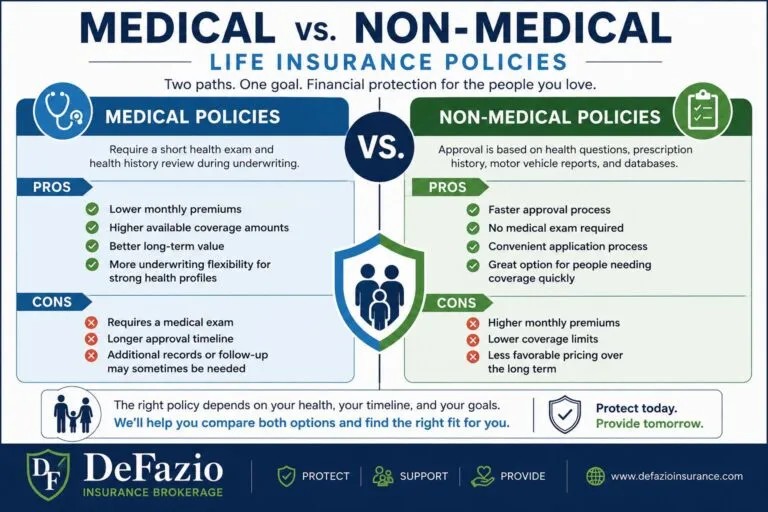
Simplified concern policies, which use health concerns without a complete paramedical test and prescription database evaluation, are more accessible for profiles that have a hard time in fully underwritten lanes while still offering meaningful survivor benefit amounts at defined premiums. Guaranteed problem policies, which require no health details, provide final expenditure protection with graded advantages for the initial duration.
Return-of-premium term structures supply a various risk/reward proposal that occasionally opens underwriting lanes for profiles where standard term is challenging our resource on term life insurance with return of premium covers this choice. And our resource on is Guardian Life a good insurance provider covers one carrier understood for favorable permanent underwriting in specific complex-profile categories. Underwriting guides for typical disqualifier categories and alternative coverage structures. Specialized underwriting resources for particular conditions, visa profiles, and coverage timing decisions.
Impaired threat life insurance, likewise known as high-risk life insurance, is a possibility for those who believe they might have problem certifying for coverage. It provides coverage choices to individuals who don't fit into the basic score classifications for traditional life insurance policies. Due to higher threat the premiums are frequently high and some policy options may use lower coverage amounts, however you still have choices to secure protection for your enjoyed ones.
Each provider has its own guidelines, but high-risk habits and conditions could consist of: Your existing health, past medical diagnoses, and how well serious conditions are managed are some of the primary aspects insurers consider to identify the threat in insuring you. Some typical health conditions that frequently fall under impaired threat consist of: Type 1 or Type 2 DiabetesHeart Illness or previous heart attackHigh blood pressureCancer historyStroke or other neurological conditionsAsthma, COPD or other respiratory issuesMental health conditions like anxiety or anxiety Other than health aspects, your daily routines might likewise impact your life insurance coverage eligibility, approval, coverage amount and premiums.
Dual-Eligible Medicare Medi-CalProtecting Families with Risk Coverage
These include: RoofersConstruction employees Pilots or aviation professionalsOil rig workersEmergency responders like firefightersWhen somebody has one (or more) way of life elements or higher-risk conditions, it can impact the capability to get a policy and the premium rates. Impaired danger life insurance coverage works the exact same method as a standard policy.
: Well handled health conditions can help you qualify for lower rates in contrast to when insurers recognize patterns of neglect around medication, follow-up and treatment strategy. Cigarette smokers generally pay more premium in comparison to non-smokers. High-risk job functions suggest a greater possibility of injury or mishaps, so exceptional expenses might rise.
Each insurance coverage company has its own category system, but usually, the five categories are: People with exceptional mental and physical health, no weight concerns, and total really few risk aspects. A little percentage of people receive this.: Overall good physical and mental health however may have small risk, such as being somewhat obese.

, so many individuals assume that they don't certify for protection.
Integrating Life Insurance with Special Needs Trust Planning
You still have choices and that's when impaired danger life insurance comes into the photo. Keep in mind: You can get life insurance coverage with a medical condition.
Whether you have medical or non-medical high-risk aspects, you still likely have choices. The key is to match the policy choices to your objectives and present monetary or personal circumstances.
It is a practical alternative for those with crucial health issues looking for ensured approval but at a greater premium and lower protection amount. In many cases, these policies consist of a waiting duration of 2 to 3 years for non-accidental deaths before full benefits use. Streamlined concern policy type is another no-exam alternative that skips physical laboratory tests, but involves evaluation through a health survey and data checks.
The costs are typically lower than ensured concern policies however higher than conventional completely underwritten policy types. Term life insurance coverage offers coverage for a set period of 10-40 years that stays the same throughout the policy's term. It can be an ideal choice for those looking for cost effective coverage for short-term needs and covering major financial responsibilities.
Managing Life Insurance Needs for Diabetic Applicants
Entire life insurance deals long-lasting protection with money value build-up. It frequently comes at a greater expense and those with fairly stable health conditions who don't mind going through a medical test might open higher protection. But particular variations like final expenditure insurance might be ideal for covering smaller protection needs. Here's how you can choose: Know the severity of your circumstance to understand the schedule of policy options. Avoid presuming and rather make comparisons across numerous insurers. Not all insurers may use similar protection alternatives and ensured problem is not your only alternative. Different insurance providers might assess threat in a different way, so always compare quotes.
Timing matters, so wait if your condition is improving to certify for better options later. Even as an impaired-risk candidate, you may still be able to get protection.
Here are some tips you may follow: Ensure that your condition is well handled and you follow the treatment strategy. Prevent using immediately after a condition is identified.
Download and finish any relevant surveys showed based off the preliminary questionnaire.
Life insurance coverage can be complicated, specifically when it comes to underwriting. This post seeks to clarify life insurance underwriting by providing clear, accurate details to assist you make notified decisions.
Protecting Assets with Specialized Risk Coverage
Most business now offer fast underwriting options, which allow you to minimize the time essential to get guaranteed. This indicates you might get coverage the fastest method without jeopardizing on thoroughness in its appraisal. Stay ahead of the industry with unique function stories on the top business, specialist insights and the current news provided directly to your inbox.
While it's true that health plays a large role in underwriting, insurance companies consider numerous aspects, consisting of age, way of life, and household case history. Even if you have some health issues, you can still find competitive rates customized to your scenario. It's everything about discovering the best policy that matches your requirements and situations.
Each policy type, the amount of protection you desire, and the examination will depend on it. For many policies, particularly those with lower protection amounts, the procedure can be easy and does not require much time. Some even offer no-exam policies, which count on existing medical records and other data and make determinations based upon that.

Latest Posts

Why Custom Risk Underwriting Matters in 2026
Key Advantages of Specialized Risk Policy Models
Finding Term Coverage for HIV-Positive Applicants