All Categories
Featured
Top Benefits of Specialized Impaired Policy Models
Essential Insurance Solutions for Special Needs Trusts
Critical Travel Health Insurance for Chronic Conditions
Top Benefits of Specialized Impaired Policy Models
Table of Contents
By Damian Tysdal, accredited travel insurance coverage agent considering that 2006 Upgraded 12 September 2026In shortOutside the United States your medical insurance pays little or absolutely nothing and Medicare pays absolutely nothing, so the medical benefit in a travel insurance coverage strategy is what pays the hospital and the flight home. Set $100,000 of emergency situation medical as the floor for a journey abroad, $250,000 or more for a cruise or a traveler over 65, and compare intend on rate from there.
Outside the United States most strategies pay little or absolutely nothing, Medicare pays absolutely nothing at all, and on a cruise ship the medical center does not even request your insurance card. Travel medical insurance coverage is what pays the healthcare facility, the physician and the flight home when you get ill or harm away from home.
The concern underneath every travel medical concern is the very same one: if I get hurt over there, who pays, and do I need to pay first? Here is the truthful response for each type of protection individuals already have. What you have Outside the United States On a cruise liner Medicare Pays absolutely nothing, apart from a couple of narrow border cases.
Special Needs Plan AdvisorAnalyzing Standard and Impaired Risk Insurance Costs
After that, absolutely nothing. Medigap plans C, D, F, G, M and N Pay 80 percent of emergency situation care in the very first 60 days of a trip, after a $250 deductible, as much as $50,000 in your life time. No evacuation. Very same rule once the ship is more than six hours from a United States port.
Special Needs Plan AdvisorSome spend for emergency situations abroad, lots of do not, and none pay for evacuation. Like abroad. Employer or marketplace health strategy Differs. Many pay nothing abroad. The ones that do treat you as out of network, desire the expense paid first, and pay absolutely nothing to fly you anywhere. Ship medical centers do not expense medical insurance at all.
A travel insurance coverage strategy Pays the healthcare facility and the physician up to the plan's medical limitation, and pays to move you to a better hospital and home under the evacuation limit. Very same, and it is the only thing that does. The useful response to "do I have to pay first" is: sometimes.
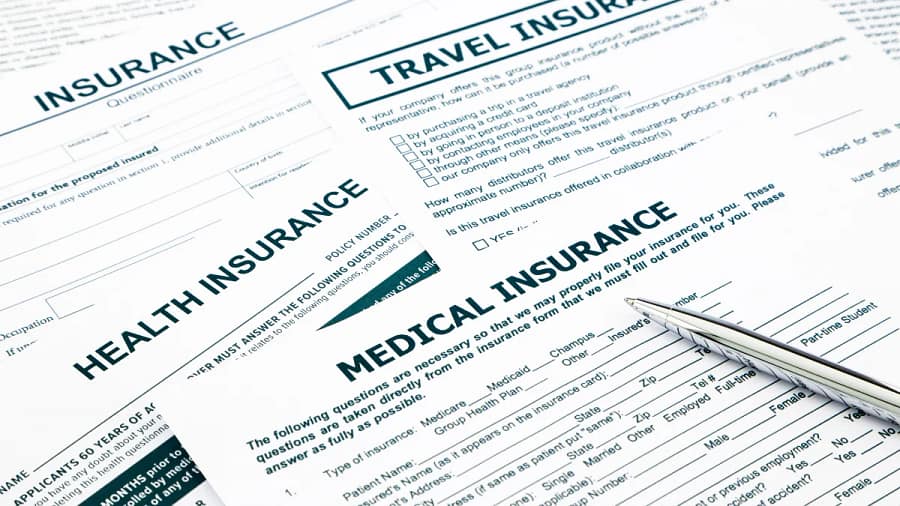
The emergency situation medical limit pays the health center. The evacuation limit pays to move you to a healthcare facility that can treat you and then home.
Emergency medical: at least $100,000 for a journey outside the United States. $250,000 or more for a cruise, a remote destination, a long trip or a traveler over 65, since a week in a foreign hospital can pass $100,000 on its own.
Complex Needs Trust Insurance Integration Strategies
These are the plans I would price initially when the health center bill is the concern. All of them are on the contrast, so you can see them priced for your journey next to each other. Limits were examined each insurance company's plan page on 12 September 2026; the business links go to our full reviews.
That covers a broken wrist and an emergency clinic go to. It does not cover a week in a healthcare facility or a surgical treatment abroad, which is what the plan is for. Primary protection pays initially. You file the claim with the travel insurance provider and you are done. Secondary coverage pays after any other insurance coverage you have, which can imply filing with your health plan first, waiting on its answer, and then filing the rest with the travel insurance company.
Main is faster and includes less documents, and it deserves having (7 Corners Trip Security Option, Tin Leg Gold and Trawick Path Premium pay primary), however a $250,000 secondary limitation protects you better than a $50,000 main one. The majority of people need to purchase the bundle plan, because they have actually prepaid money on the line and the medical advantage includes it.
Medical inside a bundle strategy A standalone travel medical strategy What it covers Cancellation, interruption, medical, evacuation, hold-ups and bags, all in one. Medical costs and evacuation abroad. Little or no cancellation coverage. Who it is for Anybody with prepaid, non-refundable cash on the line. Someone with nothing pre-paid to lose, a long stay abroad, a visitor to the United States, or a trainee.

Latest Posts

Finding Medical Safety for Global Trips Abroad
Top Benefits of Specialized Impaired Policy Models
Essential Insurance Solutions for Special Needs Trusts